Pre-Retiree
Solve healthcare before you pick a date. Know your coverage and cost until Medicare. It often decides whether an early exit works
Loading planner profile...
Financial planning isn't one-size-fits-all. I specialize in helping individuals and families navigate the complex financial crossroads of life, focusing heavily on these unique groups and the major moments that define their journeys.
Pre-Retiree
Solve healthcare before you pick a date. Know your coverage and cost until Medicare. It often decides whether an early exit works
Retirees or Seniors
Medicare premiums are based on income from two years ago. Check how big withdrawals or Roth conversions affect them before you act.
Working in Retirement
Work income eases early withdrawals. Claiming Social Security before full retirement age? High earnings can temporarily cut benefits.
Early Retirement or Financial Independence
Years between leaving work and Social Security are often low-tax. Consider Roth conversions, but watch the impact on health costs.
End of Life and Legacy Planning
Beneficiary forms override your will on retirement accounts and life insurance. Review them every few years and after major changes.
Sudden Wealth or Inheritance
Don't rush. Park it somewhere safe, learn the tax rules, including inherited IRA deadlines, then decide how it fits your goals.
Certified Financial Planners have a proven blueprint for success—but your planner builds it entirely around you.
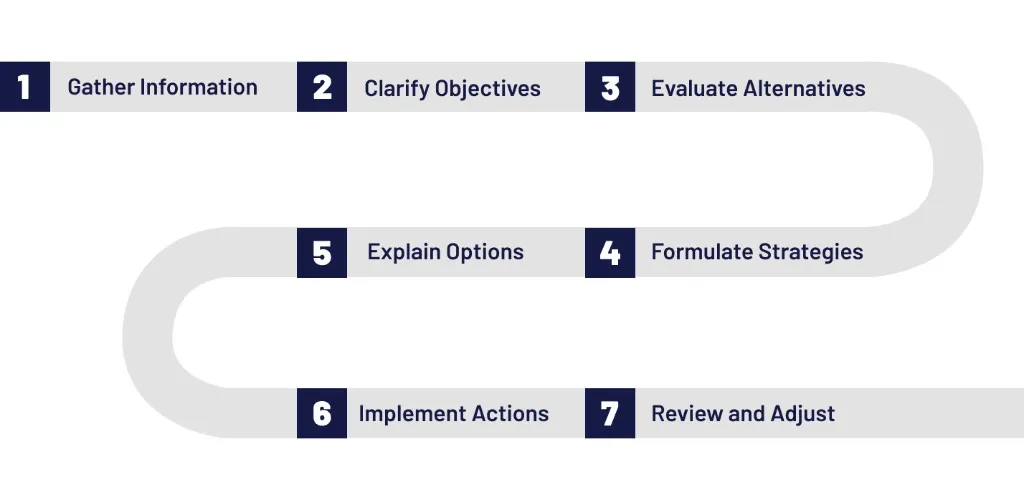
Summarized from the CFP® Board's Practice Standards. cfp.net
I'm a CFP® professional and an active 911 paramedic with 15+ years in EMS. That work shapes how I plan: assess first, treat what's most urgent, and keep watching for what could change. Most of my clients are high-income professionals in their 50s and early 60s: executives, pharma and medical device leaders, tech professionals, and business owners. They've saved well. They want to know if they can step back from full-time work without risking their health coverage, taxes, or lifestyle. What sets my practice apart Healthcare isn't an afterthought. Leaving work before Medicare means sorting out coverage, cost, and how your income affects premiums. Those choices tie directly to taxes and withdrawals, so I plan them together around four pillars: Healthcare: bridging coverage until Medicare Taxes: timing income, Roth conversions, and withdrawals Income: turning savings and Social Security into a reliable paycheck Portfolio risk: aligning investments with when you'll need the money Many clients also use my Consulting Bridge. Part-time consulting, coordinated with your portfolio and withdrawal strategy, can pull your exit date forward. It reduces early withdrawals, adds flexibility on taxes and healthcare, and lets you leave on your terms with more confidence. What clients can expect A clear picture of where you stand and what it takes to step back Specific recommendations in plain language Coordination across decisions usually handled separately Regular check-ins as laws, markets, and life change A direct working relationship with me The goal is a plan that's medically safe and mathematically sound. More control, fewer surprises. When the numbers work, Monday becomes a choice.
This material is provided for informational purposes only and does not constitute investment, tax, or legal advice. It is not a recommendation or solicitation to buy or sell any security, insurance product, or investment strategy. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal. Tax and legal matters are outside the scope of this engagement; consult your attorney, accountant, and other qualified professionals before making financial decisions. Additional information about this financial professional, including registration status and disciplinary history, is available through FINRA BrokerCheck and the SEC Investment Adviser Public Disclosure website.
Languages: English
Household Income Minimum
$0
Investable Asset Minimum
$500,000