Business Owners
Your business is a balance sheet asset, not your retirement plan. Diversify outside it, set reasonable comp and plan your exit years ahead.
Loading planner profile...
Founder and Lead Advisor
CFP®, EA (IRS Enrolled Agent)
One advisor, a CFP® professional and IRS Enrolled Agent, for households approaching or in retirement, professionals with equity compensation, and business owners. Your tax and investment decisions are made together.
Business Owners
Your business is a balance sheet asset, not your retirement plan. Diversify outside it, set reasonable comp and plan your exit years ahead.
Executives
Executive pay is a tax problem first. Coordinate RSUs, bonus, NQDC elections and 401(k) contributions against your marginal bracket.
Pre-Retiree
Your last 5 to 10 working years drive the plan: max catch up contributions, build tax diversification and map your Roth conversion window.
Also: GenX, Retirees or Seniors
Compensation Changes
A raise, bonus or new grant changes your tax picture. RSUs, ISOs, NSOs and ESPP are taxed differently, so know the rules before you sell.
Retirement Planning
Keep your next several years of withdrawals in Treasuries so a bear market does not force stock sales at a low. Sequence risk, managed.
Sudden Wealth or Inheritance
Before you deploy a windfall, park it in Treasuries and build the plan. Inherited IRAs, basis step up and trusts each change the tax math.
Also: Career Changes or Job Loss, Early Retirement or Financial Independence, Starting a Business
Certified Financial Planners have a proven blueprint for success—but your planner builds it entirely around you.
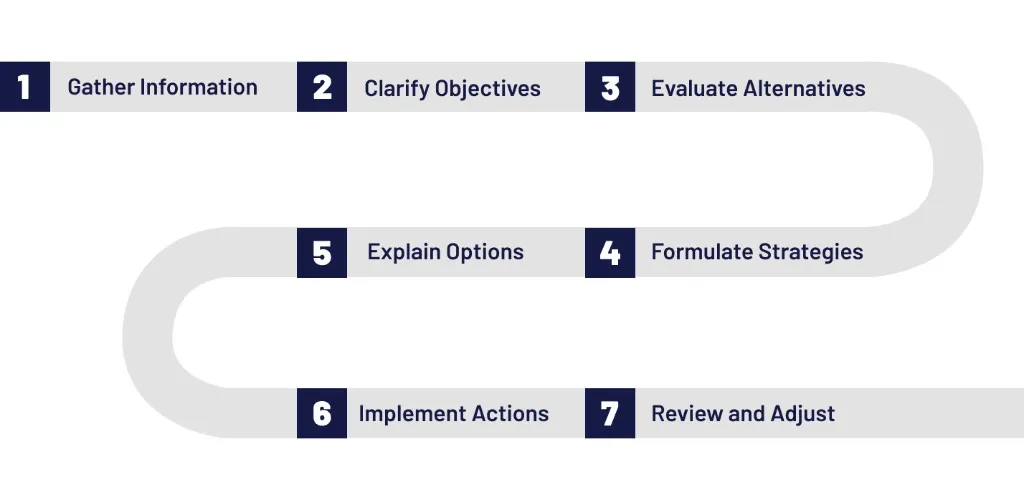
Summarized from the CFP® Board's Practice Standards. cfp.net
Valerio Wealth Management is a fee-only, fiduciary firm in Coconut Grove, Miami. I hold both the CFP® certification and the IRS Enrolled Agent credential, so the tax decision and the investment decision are made by the same person, with no handoff between a planner and a CPA. Every recommendation starts from the plan: what the money has to do, and when. Roth conversions, withdrawal order, asset location, equity compensation and charitable giving are weighed with the portfolio rather than after it. Portfolios use low-cost, broadly diversified funds, held in your name at an independent custodian. The bond share is sized to the withdrawals a household expects over the next several years, so a stock downturn does not force a sale. After a 30-minute introductory call at no cost, the work moves from discovery to a written plan to implementation, then continues with regular reviews and year-round tax planning. Meetings are by video or at the office by appointment. I am paid only by my clients, through one published, tiered advisory fee with no asset minimum. No commissions, and no insurance or annuity sales. I provide tax planning and do not prepare tax returns.
This material is provided for informational purposes only and does not constitute investment, tax, or legal advice. It is not a recommendation or solicitation to buy or sell any security, insurance product, or investment strategy. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal. Tax and legal matters are outside the scope of this engagement; consult your attorney, accountant, and other qualified professionals before making financial decisions. Additional information about this financial professional, including registration status and disciplinary history, is available through FINRA BrokerCheck and the SEC Investment Adviser Public Disclosure website.
Languages: English
Compensation Methods
Fee Only
Fee-only means a CFP® professional may describe his or her practice as "fee-only" if, and only if, all the planner's compensation from all client work comes exclusively from clients in the form of fixed, flat, hourly, percentage, or performance-based fees.
Household Income Minimum
No minimum
Investable Asset Minimum
No minimum