Business Owners
Don’t let your business become your entire financial plan. Build wealth outside of it and create flexibility for whatever comes next.
Loading planner profile...
Vice President
CFP®
Financial planning isn't one-size-fits-all. I specialize in helping individuals and families navigate the complex financial crossroads of life, focusing heavily on these unique groups and the major moments that define their journeys.
Business Owners
Don’t let your business become your entire financial plan. Build wealth outside of it and create flexibility for whatever comes next.
Millennials & GenZ
Don’t build your life around a financial plan. Build a financial plan around the life you actually want to live.
Pre-Retiree
Don’t just plan to retire. Plan what you’re retiring to. Knowing how you want to spend your time should shape how you use your money.
Career Changes or Job Loss
Give yourself financial breathing room. Keeping expenses flexible and cash available gives you more freedom to choose what comes next.
Early Retirement or Financial Independence
Financial independence isn’t just about having enough to stop working. It’s about having the freedom to decide what you want to do next.
Retirement Planning
Retirement planning isn’t about reaching a magic number. It’s about creating the flexibility to spend your time and money on what matters.
Certified Financial Planners have a proven blueprint for success—but your planner builds it entirely around you.
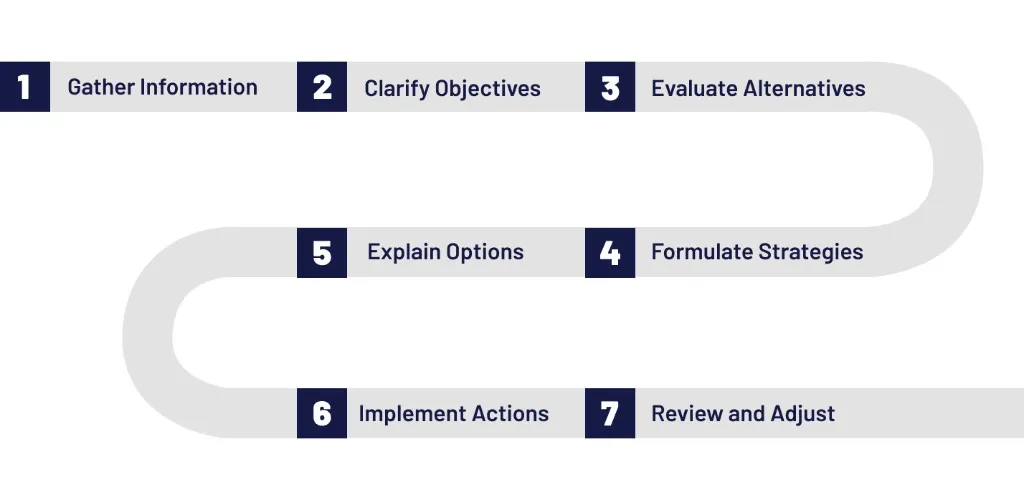
Summarized from the CFP® Board's Practice Standards. cfp.net
I’ve spent a lot of my life figuring things out on my own—and questioning expectations about what we’re supposed to do and how life is supposed to look. Some of that came naturally. Some came from experience. Losing my partner at a young age fundamentally changed how I think about time and what it means to actually live while we can. Years later, being diagnosed with ADHD in my early 30s made me reconsider assumptions I had made about myself and the way I was “supposed” to operate. Those experiences reinforced something I’ve come to believe pretty strongly: The default isn’t necessarily wrong. But it should be questioned. That philosophy shapes the way I think about financial planning, too. We’re often handed a default path: build a career, work for 40 years, save consistently, retire in our 60s, and finally enjoy the freedom we’ve spent decades preparing for. But that doesn’t have to be the only path. Maybe you want to retire early. Maybe you want to take a few years off, change careers, travel more, work less, give more, or simply reach the point where working becomes a choice rather than an obligation. I’ve spent more than a decade in financial services helping people navigate decisions like these. I completed college in three years when I was told it wasn’t possible and earned my CFP® certification in 2020. Along the way, I learned that sometimes success isn’t about following the conventional path; it’s about finding the approach that works for you. At Kane Company Wealth Management, we help individuals and families understand what’s possible, question the financial defaults they’ve inherited, and build a plan around what actually matters to them. Investment management, tax prep and planning, risk management, and retirement planning are all important—but they’re tools, not the destination. The real question is: What do you want your money to make possible? Book a meeting with me today to find out how you can start living your best life.
This material is provided for informational purposes only and does not constitute investment, tax, or legal advice. It is not a recommendation or solicitation to buy or sell any security, insurance product, or investment strategy. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal. Tax and legal matters are outside the scope of this engagement; consult your attorney, accountant, and other qualified professionals before making financial decisions. Additional information about this financial professional, including registration status and disciplinary history, is available through FINRA BrokerCheck and the SEC Investment Adviser Public Disclosure website.
Household Income Minimum
No Minimum
Investable Asset Minimum
$250,000