Business Owners
Pay yourself a regular salary and fund your retirement plan before reinvesting every spare dollar back into the business.
Loading planner profile...
I work with people who have done well and want a second set of eyes before the big decisions: retirement timing, turning savings and pensions into reliable income, and keeping taxes from eroding the plan. As a CFP® professional and Enrolled Agent, I plan your investments and taxes together, so every recommendation accounts for both. My investing approach is evidence-based and low-cost, and my job is to help you make clear decisions and stick with them. Below are the clients I serve and the milestones I help them through.
Business Owners
Pay yourself a regular salary and fund your retirement plan before reinvesting every spare dollar back into the business.
Government & Military
Treat your pension as the safest part of your portfolio. It often lets the rest of your savings invest for long-term growth.
Pre-Retiree
The years around retirement matter most. Know where your income comes from in a down market before you need it.
Also: Teachers & Educators, Working in Retirement
Early Retirement or Financial Independence
Before you leave work, know how you’ll cover health insurance and income until pensions and Social Security begin.
Retirement Planning
Plan retirement income around taxes, not just returns. The order you draw from accounts can matter as much as how they’re invested.
Starting a Business
Open a separate business account on day one and set aside a share of every payment for taxes.
Also: Buying a Home and Relocation, Sudden Wealth or Inheritance
Certified Financial Planners have a proven blueprint for success—but your planner builds it entirely around you.
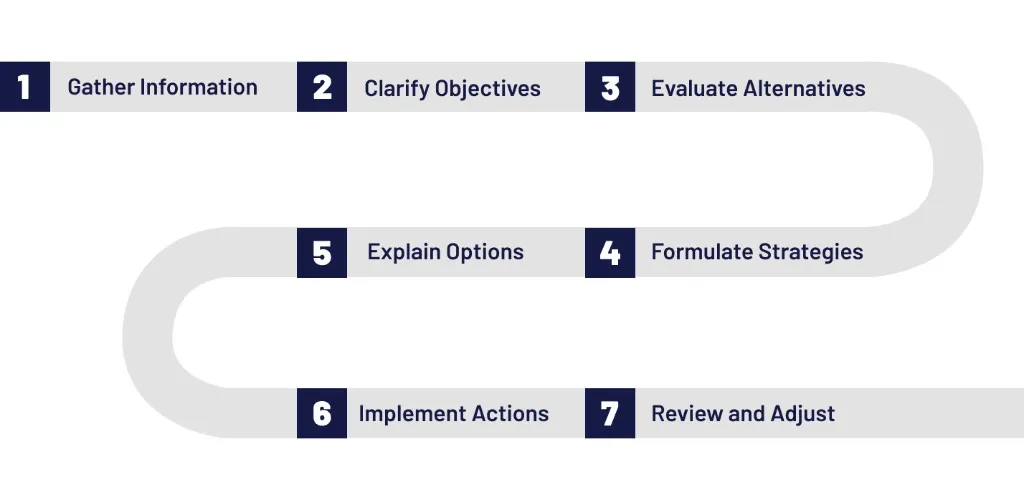
Summarized from the CFP® Board's Practice Standards. cfp.net
Most of the people I work with have done well on their own. They’ve saved, invested, maybe built a business or served a full military or federal career. What they want now is a second look from someone who sees the whole picture before the big decisions arrive: when to retire, how to turn savings into a paycheck, and how to keep taxes from quietly eating away at the plan. That whole-picture view is what sets my practice apart. I’m a CFP® professional and an Enrolled Agent, so your investments and your taxes get planned in the same conversation instead of in two offices that never talk to each other. And because I’m the only advisor here, you work with me directly every time. Here’s what working together looks like: 1. Intro call. We talk about what’s on your mind and whether I’m the right fit. If I’m not, I’ll tell you. 2. Discovery. We gather the full picture: accounts, income sources (including pensions), tax returns, goals, and the questions that keep you up at night. 3. Your plan. I build a plan covering retirement income, investments, and taxes, and we walk through it together until it makes sense to you. 4. Implementation. We put the plan to work with a low-cost, diversified portfolio built on evidence, not predictions. 5. Ongoing partnership. Life changes, tax law changes, and markets move. We revisit the plan regularly, adjust when it matters, and I help you stay steady when the headlines get loud. The goal is simple: confident decisions now, and no second-guessing the ones you’ve already made.
This material is provided for informational purposes only and does not constitute investment, tax, or legal advice. It is not a recommendation or solicitation to buy or sell any security, insurance product, or investment strategy. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal. Tax and legal matters are outside the scope of this engagement; consult your attorney, accountant, and other qualified professionals before making financial decisions. Additional information about this financial professional, including registration status and disciplinary history, is available through FINRA BrokerCheck and the SEC Investment Adviser Public Disclosure website.
Household Income Minimum
No minimum
Investable Asset Minimum
$500,000