Executives
Your equity comp is already your paycheck and your bonus. Don't let it be your portfolio too.
Loading planner profile...
Financial planning isn't one-size-fits-all. I specialize in helping individuals and families navigate the complex financial crossroads of life, focusing heavily on these unique groups and the major moments that define their journeys.
Executives
Your equity comp is already your paycheck and your bonus. Don't let it be your portfolio too.
Retirees or Seniors
The gap between your last paycheck and your first required withdrawal is your lowest-tax decade. Use it.
Women & Female Leaders
In a divorce settlement, $500,000 in a house and $500,000 in a 401(k) are not the same $500,000. Ask about the tax.
Divorce Planning
Your lawyer divides the past. Nobody divides your future unless you ask for it.
Early Retirement or Financial Independence
The Financial Independence math usually works. The health insurance between now and Medicare is what breaks it.
Retirement Planning
Stop asking whether the balance is big enough. Ask what monthly paycheck it actually buys.
Certified Financial Planners have a proven blueprint for success—but your planner builds it entirely around you.
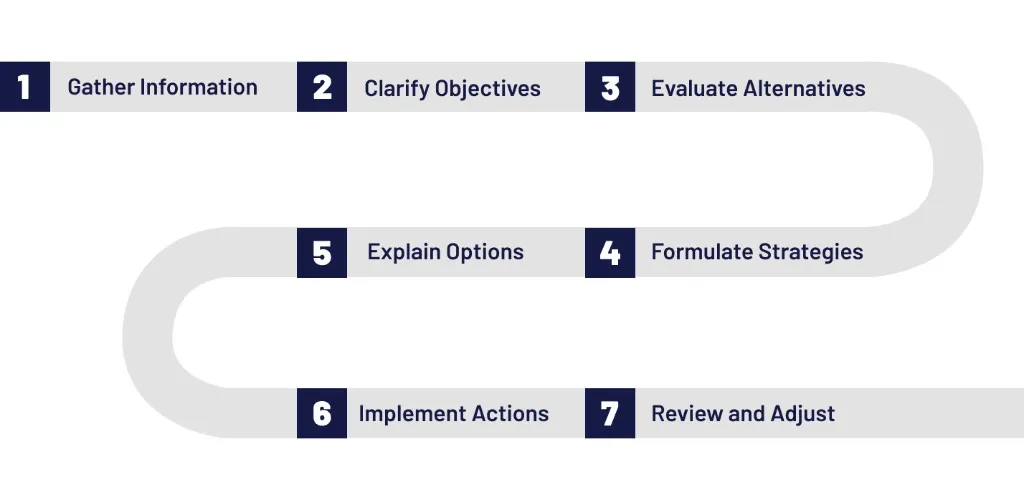
Summarized from the CFP® Board's Practice Standards. cfp.net
I run a fee-only fiduciary practice in White Plains, NY. Most of my work sits at the point where a financial life is being restructured rather than simply managed. Divorce is the main focus: I serve as a financial neutral in mediation, as the analyst working alongside matrimonial counsel, and as the planner clients keep once the case is over. I also do comprehensive planning for people who aren't in a transition at all. What sets the practice apart is that several disciplines sit in one seat. I hold the CFP®, CFA, EA, and CDFA® designations. The tax consequences of a settlement, the way a portfolio actually behaves once it's divided, and the plan that has to work for the next thirty years don't get handed off to three different people. The Enrolled Agent piece matters more than it sounds, because most decisions in a divorce are tax decisions wearing a different name. What clients can expect is numbers they can defend. I build analyses from the underlying account statements, not from summaries, and I write deliverables so a client can put them in front of an attorney, a mediator, or a spouse and stand behind every line. I'm also clear about where my work stops: property characterization and legal conclusions belong to counsel, and I say so rather than guessing. If you're facing a decision and want to understand the financial consequences before you make it, that's the conversation I'm built for.
This material is provided for informational purposes only and does not constitute investment, tax, or legal advice. It is not a recommendation or solicitation to buy or sell any security, insurance product, or investment strategy. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal. Tax and legal matters are outside the scope of this engagement; consult your attorney, accountant, and other qualified professionals before making financial decisions. Additional information about this financial professional, including registration status and disciplinary history, is available through FINRA BrokerCheck and the SEC Investment Adviser Public Disclosure website.
Household Income Minimum
$0
Investable Asset Minimum
$0