GenX
Before you pick a retirement date, picture what you’re retiring into. Once you know what the money is for, every other choice gets easier.
Loading planner profile...
I work with people in their late 50s and 60s who’ve saved well and want to know what it’s for. Most come to me around retirement, a job change, an inheritance or a big tax decision, and want one planner to see the whole picture.
GenX
Before you pick a retirement date, picture what you’re retiring into. Once you know what the money is for, every other choice gets easier.
Pre-Retiree
Before your last day, decide where each paycheck will come from and in what order. The order you draw from accounts can save you thousands.
Retirees or Seniors
You saved so you could live. A clear plan shows what you can safely spend each year, so you can enjoy it without worrying about running out.
Also: Working in Retirement
Career Changes or Job Loss
Pause before you sign or roll anything over. Severance, benefits and your 401(k) can wait a few weeks. This may be your retirement date.
Retirement Planning
Social Security is one of the biggest decisions you’ll make, and it’s hard to undo. Run the numbers on your claiming age before you file.
Sudden Wealth or Inheritance
Don’t rush. Park an inheritance somewhere safe for six months, let things settle, then decide. Few good money moves are made in a hurry.
Also: Buying a Home and Relocation, Caregiving for Aging Relatives, Compensation Changes, Death in the Family, Early Retirement or Financial Independence, End of Life and Legacy Planning, Funding Education, Getting Married and Starting a Family, Starting a Business, Widowhood
Certified Financial Planners have a proven blueprint for success—but your planner builds it entirely around you.
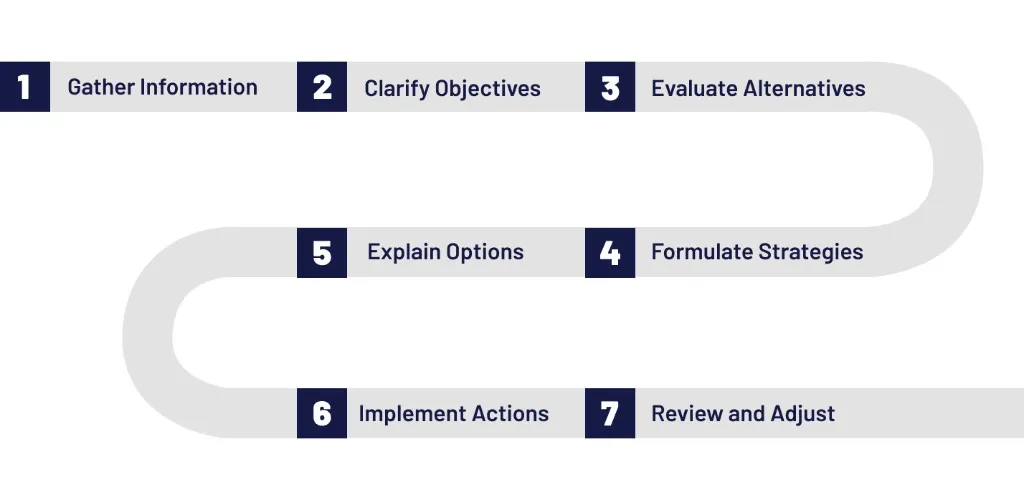
Summarized from the CFP® Board's Practice Standards. cfp.net
Working together starts with a free 30-minute intro call. It’s a conversation about what’s on your mind and whether I’m the right fit. If it feels right, here’s what happens next: 1: Proposal. I come back with a recommendation, exactly what it would cost, and what I’d focus on for you. There’s no pressure to decide on the spot. 2: Discovery. We start with your life, not your portfolio: what a great next chapter looks like, what matters most and what keeps you up at night. 3: Plan building. I show you two or three paths with the tradeoffs laid out, and we decide together. 4: Action. You get a clear written plan, and we take the first steps together so it doesn’t sit on a shelf. For ongoing clients, the work keeps going. You get a spring review of last year, your goals and your tax return, and an autumn review of your investments and year-end tax moves. In between, I send a short monthly check-in and reach out first when something changes. I also coordinate with your CPA and estate attorney when it helps. What sets the practice apart is that you work with me directly at every step. I’m a fee-only CFP® professional, I keep the practice small on purpose, and your planning and investments are handled together in one place.
This material is provided for informational purposes only and does not constitute investment, tax, or legal advice. It is not a recommendation or solicitation to buy or sell any security, insurance product, or investment strategy. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal. Tax and legal matters are outside the scope of this engagement; consult your attorney, accountant, and other qualified professionals before making financial decisions. Additional information about this financial professional, including registration status and disciplinary history, is available through FINRA BrokerCheck and the SEC Investment Adviser Public Disclosure website.
Compensation Methods
Fee Only
Fee-only means a CFP® professional may describe his or her practice as "fee-only" if, and only if, all the planner's compensation from all client work comes exclusively from clients in the form of fixed, flat, hourly, percentage, or performance-based fees.
Household Income Minimum
No minimum
Investable Asset Minimum
$250,000